
Carbon Border Adjustment Mechanism CBAM
The carbon border adjustment mechanism (CBAM) is a new tax aiming to ensure that highly traded, carbon intensive goods which are imported into the UK face a comparable carbon price to that paid by manufacturers producing the same goods in the UK. In the UK, for direct emissions, manufacturers can be subject to carbon pricing under the UK Emissions Trading Scheme (ETS). CBAM will apply from 1 January 2027 to goods from these industrial sectors: aluminium, cement, fertiliser, hydrogen, iron and steel.
CBAM is intended to prevent carbon leakage by ensuring that domestic decarbonisation efforts lead to real global emissions reductions rather than shifting production abroad. Carbon leakage occurs when industries relocate to countries with weaker carbon pricing, increasing overall emissions. CBAM addresses this by applying a comparable carbon cost to imports of high emission goods, aligning them with the costs faced by UK producers under the UK Emissions Trading Scheme (ETS). By doing so, it protects the competitiveness of UK industry, encourages continued investment in low‑carbon production, and ensures a level playing field. The CBAM tax rates will be linked to UK ETS costs, adjusted to reflect any free allowances or discounts received by domestic producers.
Between 2023 and 2025 the UK developed CBAM through a staged series of consultations and enabling legislation. An initial consultation on “addressing carbon leakage risk to support decarbonisation” (March–June 2023) led to a December 2023 government response confirming that a UK CBAM would be introduced to tackle carbon leakage linked to domestic carbon pricing. A second (March–June 2024) "consultation on the introduction of a UK carbon border adjustment mechanism" then set out detailed design and administration proposals, with the October 2024 response confirming key scope decisions, including that glass and ceramics would not be in scope from commencement.
The Finance Act 2025 gave HMRC powers to prepare for CBAM and to obtain specified UK ETS information from HM Treasury and HMRC to support its design and operation. A technical consultation on the draft CBAM legislation (March–July 2025) refined the mechanics of the regime, including the frequency of accounting and payment and the data required in returns. As announced at Budget 2025, indirect emissions associated with CBAM goods will not be covered at the 1 January 2027 start date, reflecting continued support for the Energy Intensive Industries Compensation Scheme.
For further information see Policy paper Carbon Border Adjustment Mechanism Published 26 November 2025
[edit] Related articles on Designing Buildings
- A zero-carbon UK by 2050?
- Black carbon.
- Blue carbon.
- Biogenic carbon.
- Biologic carbon sequestration.
- Carbon capture.
- Carbon cycle.
- Carbon dioxide.
- Carbon emissions.
- Carbon intensity.
- Carbon sequestration.
- Carbon.
- Embodied energy in construction
- Energy balancing.
- Energy Intensive Industries Compensation Scheme.
- Energy supply.
- Energy white paper.
- Geologic carbon sequestration.
- Generation nuclear.
- Net zero and green jobs.
- Net zero carbon 2050.
- Organisations prompt government to Build Back Green.
- Power generation.
- Renewable energy.
- The Government's 10-point plan: what's missing?
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Introduction to radon awareness
New technical information sheet published by CIOB.
Updated supplier guide can help electrical contractors engage with NHP.
CIAT confirm the winners of the 2026 architectural technology awards.
Government launches a one stop shop for flood preparedness.
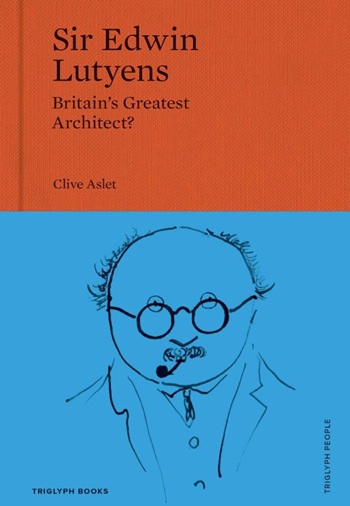
Sir Edwin Lutyens: Britain's greatest architect? Book review.
CIOB publishes free template to help assess and manage risks.
ECA's reflections on Party Conference season
Burnham wants to be confident of winning before asking for a fresh mandate.
New Chief Construction and Scientific Adviser
Sergio Cavalaro, Professor of Infrastructure Systems at Loughborough University.
Building safety levy for England
CIAT publish estimator tool for members.
Water sector faces a growing crisis that could slow the delivery of vital infrastructure.
Undervaluing our industrial past
Heritage value changes as taste for building styles changes.
Changing expectations around competence and compliance
New information sheet from CIAT.